Oil Above 100 is a Real Supply Shock but NOT a Permanent Price Regime
Brent's move to US$105.26 per barrel on 10 September is not a purely speculative war premium. The physical market has lost several million barrels per day of Gulf supply, global inventories have been drawn down heavily, and the routes that should provide relief are themselves under pressure. EIA estimates that 6.7 million barrels per day of Gulf crude production was shut in during August. The IEA estimates that observed inventories had fallen by 410 million barrels between the start of the war and the end of July. Diesel and jet fuel are tighter than the headline crude benchmark suggests because Middle Eastern refining and product exports have also been disrupted.
Executive Summary
Brent's move to US$105.26 per barrel on 10 September is not a purely speculative war premium. The physical market has lost several million barrels per day of Gulf supply, global inventories have been drawn down heavily, and the routes that should provide relief are themselves under pressure. EIA estimates that 6.7 million barrels per day of Gulf crude production was shut in during August. The IEA estimates that observed inventories had fallen by 410 million barrels between the start of the war and the end of July. Diesel and jet fuel are tighter than the headline crude benchmark suggests because Middle Eastern refining and product exports have also been disrupted.
The near-term balance therefore retains a bullish skew. Yet oil above US$100 already discounts a serious and persistent disruption. The forward curve falls sharply into 2027, demand is weakening under the weight of high prices, and pipelines, ship-to-ship transfers and strategic stocks are gradually changing the market's ability to absorb the shock. A credible reopening of Hormuz would release stored barrels and restart shut-in production quickly enough to cause a violent reversal before the physical system fully normalises.
Our base case is Brent at US$95-115 over the next month, US$85-100 at the end of 2026 and an annual average of US$70-90 in 2027. We remain tactically constructive over the next month, but we do not view US$100-plus Brent as a stable long-run price regime. The position should be revised if insured Hormuz flows recover consistently or, in the other direction, if Gulf production remains several million barrels per day below pre-war levels into 2027. Confidence is medium because dark shipping obscures true flows and a single diplomatic or military event can move the front of the curve by double digits.
KEY NUMBERS
US$105.26 | US$100.04 | 6.7 mb/d | 410 million bbl |
BRENT AT 12:15 GMT | WTI AT 12:15 GMT | AUGUST GULF SHUT-INS | STOCK DRAW SINCE WAR START |
Brent Has Returned to Triple Digits
At 12:15 GMT on 10 September, Reuters reported November Brent futures at US$105.26 per barrel and October WTI at US$100.04. Both contracts were roughly 4 per cent higher on the day. Brent had risen by more than 30 per cent from its early-August low. Dated Brent, the physical benchmark against which much of the world's crude is priced, had already traded above US$100 from 3 September. That sequence matters. Physical pricing tightened before the latest front-month futures surge, which supports the argument that prompt scarcity is real rather than an isolated reaction to military headlines.
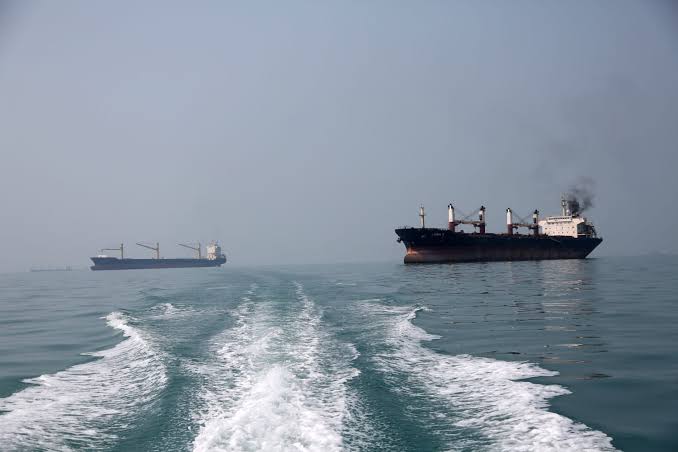
The immediate trigger was the largest declared wave of attacks on shipping since the six-month war began. The United States said it rendered five Iranian tankers inoperable on 8 September. Iran then said it attacked two US vessels, eight oil tankers and additional non-compliant ships around Hormuz. The broader total remains disputed. The International Maritime Organization had independently confirmed damage to two merchant vessels on 9 September by the report cut-off. The correct distinction is therefore between a confirmed escalation and the larger attack totals claimed by belligerents.
How the Price Path Reached This Point
DATE | DEVELOPMENT | OIL MARKET CONSEQUENCE |
|---|---|---|
28 Feb | War begins and Hormuz traffic collapses | Gulf output is shut in and emergency stocks become the first buffer |
11 Mar | IEA members approve a 400 million barrel emergency release | The largest collective release in IEA history slows but does not end stock depletion |
Jun to Jul | A US-Iran memorandum briefly improves transit before breaking down | Brent falls as low as US$69 on 2 July, then reaches US$105 on 23 July |
Aug | US blockade and sanctions return while Yanbu loadings weaken | EIA estimates Gulf shut-ins rise to 6.7 mb/d |
8 to 10 Sep | Tanker attacks intensify around Hormuz and Red Sea risk rises | Brent moves above US$105 and WTI above US$100 intraday |
The Market Is Trading Duration Rather Than Direction Alone
Oil has already shown that it can collapse on credible de-escalation and rally on renewed disruption. The key question is no longer whether the conflict can move prices. It is whether restricted passage becomes a lasting operating condition. The more the market believes that ships will face mines, missiles, insurance restrictions and political clearance well into 2027, the more of the current premium moves from the front contract into deferred prices. That is the clearest test of whether US$100 oil is becoming structural.
Pre-war Flows Cannot Be Replaced Quickly
The Strait of Hormuz normally carries close to one-fifth of global oil supply. The IEA estimates that 19.87 million barrels per day of crude, condensate and refined products transited the strait in 2025, with roughly 80 per cent travelling to Asia. EIA uses a slightly broader petroleum-liquids definition and estimates 21.6 million barrels per day in the fourth quarter of 2025. The figures should not be treated as identical, but both show the scale of the exposure: a shipping corridor only a few miles wide connects a large part of Gulf production with the world market.
Current flow estimates remain far below that baseline. Reuters' 9 September cross-provider analysis placed total Gulf oil exports, including dark crossings and bypass routes, at about 15-16 million barrels per day, compared with roughly 25 million before the war. Vortexa estimated about 15 million barrels per day in August. The IEA separately estimated July Gulf output at 23.9 million barrels per day, still 8.3 million below pre-war levels, while regional exports including bypass routes fell to 15 million barrels per day. These measures use different definitions and time periods, so they cannot be added together. Their common message is that the shortage is measured in millions of barrels per day.
Figure 1. EIA Gulf crude-production shut-ins. Values are reported data or EIA forecasts and have not been independently recalculated.
The September Forecast Was Stale Before It Was Published
EIA's September forecast was released on 9 September, but its inputs were finalised on 3 September. It therefore excludes the most recent tanker attacks. EIA still expects average shut-ins of 5.7 million barrels per day in the fourth quarter and 2.7 million in the first quarter of 2027. The latest escalation makes the near-term risk to that path asymmetric: actual shut-ins may remain higher for longer, while the forecast's eventual recovery still depends on safer shipping and workable bypass logistics.
Formal Closure Is Not the Only Constraint
A binary description of the strait as open or closed misses how the market is functioning. Ships may technically transit while the effective capacity remains low because owners, crews and insurers will not accept the risk. Mines and projectile attacks have pushed vessels away from the normal traffic-separation scheme. Alternative northern and southern corridors require coordination, security assessment and political clearance. Many tankers disable their automatic identification systems, which makes public ship counts incomplete and encourages exaggerated claims in both directions.
As of 10 September, the IMO listed 75 confirmed shipping incidents and 22 seafarer deaths in the wider Middle East theatre. It confirmed damage to HERCULES STAR and NEW ANDROS on 9 September, with one fatality aboard the former. These figures demonstrate a genuine threat to merchant shipping, but they do not validate every attack claimed by Iran. That distinction matters for price analysis because the marginal tanker is governed by expected loss, insurability and crew willingness rather than by press statements alone.
Spare Capacity Is on the Wrong Side of the Chokepoint
Under normal conditions, higher OPEC+ output could cap a rally. In this crisis, much of the spare reservoir capacity sits behind the same disrupted export routes. The IEA estimated only 1.09 million barrels per day of effective OPEC+ spare capacity in July, including just 0.07 million across the OPEC-8 under its definition. The difference between large nameplate capacity and small effective capacity is logistical: a producer cannot stabilise the market with a barrel that cannot reach a safe loading terminal.
Saudi Arabia and the United Arab Emirates do have pipelines that bypass Hormuz. The IEA estimates potential bypass capability of roughly 3.5-5.5 million barrels per day, but warns that the upper end has not been robustly tested. The UAE route to Fujairah offers limited additional room. Saudi Arabia's East-West pipeline can move crude towards Yanbu on the Red Sea, but EIA estimates that Yanbu exports fell by about half in August from July as attacks around Bab el-Mandeb disrupted the alternative corridor. Rerouting through Suez and ship-to-ship transfers can help, but both add cost, time and operational risk.
OPEC Plus Cannot Solve a Shipping War with a Quota
On 6 September, seven OPEC+ participants held October production requirements at September levels. In an ordinary market, the absence of a production increase might look bullish. Here the signal is weaker because several Gulf members are unable to produce or export at quota. The near-term balance will be decided by safe passage, export nominations and infrastructure availability rather than by the announced ceiling alone.
POTENTIAL BYPASS | 3.5-5.5 mb/d | IEA estimate for Saudi and UAE pipeline routes. Practical capacity depends on terminals, security and sustained operation. |
The Shock Absorber Has Already Been Used
The market entered the September escalation with less inventory protection than it had in March. The IEA estimates that observed global oil stocks fell by 410 million barrels between the start of the war and the end of July, an average decline of 2.7 million barrels per day. July alone produced a 69 million barrel draw, driven mainly by lower oil on water. EIA estimates an even steeper balance draw of 3.0 million barrels per day in the third quarter and 1.7 million in the fourth quarter. The exact numbers differ because the agencies use different coverage and methodologies, but both describe continuing depletion.
IEA member governments released 400 million barrels of emergency oil after the March shock. The decision bought time, but it did not recreate lost Gulf production. By July, the IEA said the pace of emergency releases had slowed. The US Strategic Petroleum Reserve stood at 294.1 million barrels on 20 August, according to the Department of Energy, after the US committed 172 million barrels to the collective action. Governments retain policy options, but repeated releases are a finite bridge and will have only temporary price impact unless physical flows improve.
Diesel and Jet Fuel Are Tighter Than Crude
The refined-product market is the most durable part of the bullish case. IEA estimates that global refinery throughput reached 80.9 million barrels per day in July but remained nearly 5 million below a year earlier. Seaborne product trade was 3.8 million barrels per day lower year on year. Diesel exports from Russia, the Middle East and Asia were down 1.3 million barrels per day, while jet fuel exports from those regions fell by about 670,000 barrels per day. Atlantic Basin middle-distillate cracks and margins reached record levels.
EIA expects US distillate stocks to fall below 100 million barrels in September and to remain below the five-year range through the end of 2026 and much of 2027. This tightness can persist even if Brent falls on a ceasefire. Refineries need feedstock, safe export routes and time to restore operations. A diplomatic headline can remove a crude risk premium in hours; it cannot rebuild product inventories or repair damaged facilities at the same speed.
What This Means for the Price Floor
The crude market is balancing through three costly mechanisms: inventory draws, demand destruction and rerouting. All three reduce the chance of an immediate shortage, but none is a free source of supply. The more stock is consumed today, the more the 2027 recovery depends on actual production returning. The more products remain scarce, the less useful it is to declare victory because the front Brent contract has softened. The entire barrel matters, not only the crude benchmark.
Backwardation Is the Market's Working Assumption
The accessible ICE snapshot from 9 September showed November 2026 Brent at US$100.45, December at US$96.52, March 2027 at US$87.84, June 2027 at US$82.75 and December 2027 at US$77.87. The curve was already sharply backwardated before Brent's 10 September intraday move to US$105.26. This structure pays a premium for immediate barrels and discounts eventual recovery. It does not guarantee lower prices, but it reveals the market's central assumption: the disruption is severe now and becomes less restrictive over time.
Figure 2. ICE Brent futures curve at 9 September 2026. Contract prices are observations, not probability-weighted forecasts.
Deferred Prices Are the Test of Permanence
A further rally confined to the front contracts would show that traders fear prompt scarcity but still expect repair and reopening. A simultaneous move above US$100 across 2027 would be more serious. It would imply that the market is no longer pricing only a logistics shock; it is pricing durable production loss, damaged infrastructure or a permanently impaired shipping regime. That is why the deferred curve matters more to the long-term thesis than another round-number break in the front month.
Positioning Raises Reversal Risk Without Cancelling the Fundamentals
The latest CFTC Disaggregated Futures Only report covers positions on 1 September and therefore predates the latest escalation. Managed-money WTI longs stood at 205,300 contracts and shorts at 111,019. Longs had risen by 8,418 during the week while shorts fell by 1,843. Funds were already leaning more bullish before Brent crossed US$100. That creates room for profit-taking on a diplomatic headline, but positioning is not a substitute for the physical data and should not be used as a stand-alone contrarian signal.
Published Forecasts Span a Wide Range
Agency and bank forecasts are not directly comparable because they use different cut-off dates, horizons and assumptions. The gap between them is still informative. EIA assumes most Middle Eastern production and trade returns towards pre-war levels by the second quarter of 2027. Goldman Sachs assumes disruptions continue into 2027 but that production adapts in the second half. HSBC describes a persistently impaired new normal. Each path produces a different answer to the same question: how much physical supply can reach consumers before demand weakens enough to balance the market?
SOURCE | CUT-OFF OR DATE | BRENT FORECAST | CENTRAL ASSUMPTION |
|---|---|---|---|
EIA | 9 Sep release | US$90 2H26; US$74 2027 average | Flows recover gradually and most production returns towards pre-war levels by 2Q27 |
Goldman Sachs | 7 Sep note | US$85 Dec 2026; US$80 2027 average | Shipping disruption continues into 2027, but adaptation and weak Chinese imports cap upside |
HSBC | 8 Sep note | US$90 2026 average; US$85 2027 average | Hormuz remains neither fully open nor fully closed and the market adapts to persistent impairment |
ICE curve | 9 Sep snapshot | US$96.52 Dec 2026; US$77.87 Dec 2027 | Market prices immediate scarcity and eventual relief; this is not a forecast |
Sources: EIA September STEO, Goldman Sachs coverage by Investing.com, HSBC coverage by Rigzone and ICE data.
Demand Is the Largest Forecast Disagreement
The IEA's August report forecasts global oil demand falling by 1.6 million barrels per day in 2026 as high prices and disrupted supply chains reduce consumption. Reuters reported that OPEC's September report still expected growth of 380,000 barrels per day after its fifth consecutive downgrade. The direction of that disagreement is more important than the apparent precision. If the IEA is closer, demand destruction will cap the price and accelerate mean reversion. If OPEC is closer while Gulf supply remains impaired, the market will need higher prices or deeper stock draws to balance.
China is the immediate swing factor. Reuters reported that Chinese buying had improved in recent weeks after months of subdued demand, while Goldman Sachs noted that imports remained well below the prior year. A sustained Chinese recovery would amplify Gulf supply losses. A renewed pullback in imports would absorb part of the shock and make the deferred curve's decline more credible.
Our Forecast Method
The scenario ranges below are analyst assumptions anchored to observed prices, the ICE curve, EIA's official path and published bank forecasts. They are not mechanically probability-weighted and they are not outputs from a proprietary oil-balance model. One-month and end-2026 figures are endpoint ranges. The 2027 figure is an annual-average range. The purpose is to show how different physical states of Hormuz translate into prices without pretending that the current military path can be forecast to the nearest dollar.
Brent Price Scenarios
SCENARIO | OPERATING ASSUMPTION | ONE MONTH | END 2026 | 2027 AVERAGE |
|---|---|---|---|---|
De-escalation and reopening | Verified ceasefire, insured passage and Gulf production restarts | US$80-95 | US$70-85 | US$60-75 |
Contained persistent disruption | Hormuz stays impaired, bypasses partly offset losses and demand weakens | US$95-115 | US$85-100 | US$70-90 |
Prolonged severe disruption | Hormuz and Red Sea routes deteriorate and Gulf output remains several mb/d below normal | US$120-150 | US$110-140 | US$100-130 |
Scenario ranges are 6:05 Markets analyst assumptions as at 10 September 2026. They are not assigned probabilities.
De-escalation and Reopening
The downside price case requires more than a political announcement. The market would need a ceasefire that produces verified passage, normalises war-risk insurance and allows production to restart. Hormuz flows would need to recover towards the levels briefly achieved during the June-July agreement, while Yanbu and Bab el-Mandeb remain usable. Stored barrels inside the Gulf and renewed emergency releases could accelerate the initial fall. Brent could move into the US$80-95 range within a month and end 2026 at US$70-85. Product prices would probably decline more slowly because inventories and refinery operations need time to recover.
Contained Persistent Disruption
This is the preferred base case. Hormuz remains dangerous and administratively restricted, but it is not completely shut. Pipelines, dark crossings, escorted transits and ship-to-ship transfers keep total Gulf exports around a reduced but workable level. Shut-ins remain close to EIA's fourth-quarter assumption, while high prices suppress demand. Brent holds a high floor and repeatedly trades above US$100 over the next month, but adaptation prevents an uncontrolled move. The price then eases as inventories rebuild and production returns during 2027.
Prolonged Severe Disruption
The upside price case requires simultaneous failure of the main escape routes. Repeated attacks on commercial tankers, physical damage to Gulf processing or export infrastructure, and a sustained threat to Yanbu or Bab el-Mandeb would remove more supply than current workarounds can replace. Brent could trade at US$120-150 over the next month and remain above US$100 through 2027 if Gulf output stays several million barrels per day below pre-war levels. Short-lived overshoots could exceed the range because prompt demand and shipping capacity are inelastic, but high prices would eventually trigger recession risk, substitution and stronger policy intervention.
The Bullish Case Can Fail Quickly
The strongest downside risk is a credible security arrangement, not a diplomatic headline. Two consecutive weeks of rising verified exports, broader insurance cover and fewer IMO-confirmed incidents would show that the effective capacity of Hormuz is recovering. Stored crude would begin to move, producers would restart wells and the front of the curve could fall before official monthly data confirmed the change. The early-July drop to US$69 demonstrates how quickly the market can remove a risk premium when it believes passage is improving.
The Mean-Reversion Case Can Also Fail
The 2027 decline would be wrong if the war damages durable infrastructure or turns restricted passage into a permanent regime. The clearest evidence would be Gulf output remaining at least 4 million barrels per day below pre-war levels into early 2027 while deferred Brent moves above US$100. Under those conditions, the market would be pricing structural supply loss rather than a temporary logistics shock. Goldman Sachs' published sensitivity places Brent above US$120 if average 2027 Gulf output remains 4 million barrels per day below pre-war levels.
The Signals That Matter
INDICATOR | BASE CASE SIGNAL | SIGNAL THAT CHANGES THE VIEW |
|---|---|---|
Hormuz barrel flows | Exports remain reduced and volatile | Two weeks above roughly 12-15 mb/d with insured passage weakens the bullish case |
Gulf shut-ins | About 5-6 mb/d persists in late 2026 | At least 4 mb/d remains offline into 2027 challenges mean reversion |
Brent curve | Front stays above deferred contracts | Deferred 2027 Brent moves above US$100 and backwardation flattens through a rally |
Products | Diesel and jet cracks remain elevated | Rapid margin compression signals that refinery and product supply is normalising |
China | Buying improves but remains price-sensitive | Sustained import recovery amplifies supply loss; another retreat caps it |
Maritime risk | Incidents remain episodic but serious | Normal insurance and falling confirmed incidents support reopening; terminal damage supports escalation |
Thresholds are analytical monitoring conditions, not automatic trading instructions.
Measurement Risk Remains High
AIS-visible traffic understates dark crossings, while a single high-flow day overstates sustainable recovery. Production shut-ins, Gulf exports and Hormuz transits are different measures and should never be added together. The IEA and OPEC demand forecasts point in opposite directions. The September EIA model also predates the latest attacks. These limitations lower confidence, but they do not erase the physical evidence. The correct response is to use ranges and explicit triggers rather than false precision.
The Position
PARAMETER | 6:05 MARKETS VIEW |
|---|---|
Direction | Tactically constructive on Brent over the next month; lower and more neutral through 2027 |
Base range | US$95-115 in one month; US$85-100 at end-2026; US$70-90 2027 annual average |
Preferred benchmark | Brent, because it is more directly exposed to Middle Eastern seaborne supply than WTI |
Thesis works if | Hormuz exports stay constrained, Gulf shut-ins remain near 5-6 mb/d and product cracks stay elevated |
Downside invalidation | Insured flows recover for two weeks, physical premiums compress and Brent falls below roughly US$90 as the curve flattens |
Upside invalidation | Gulf output remains at least 4 mb/d below normal into 2027 and deferred Brent moves above US$100 |
Analytical confidence | Medium because physical tightness is confirmed but flow measurement and event timing remain unusually uncertain |
How We Would Express the View
The research conclusion favours a tactical long bias, but it does not support chasing unhedged front-month exposure after a rise of more than 30 per cent from the early-August low. The front contract captures prompt scarcity most directly, but it also carries the largest overnight gap and ceasefire risk. A defined-risk option structure or a carefully sized position on a pullback is more consistent with the two-sided distribution than an open-ended futures position. Calendar spreads offer a cleaner test of duration: persistent backwardation supports a finite shock, while a rally in deferred contracts would confirm structural damage. These are general market observations, not personalised investment advice.
Energy equities are an imperfect substitute. Producers may benefit from higher benchmark prices, but their returns also depend on hedging, taxes, operating costs, country exposure and broader equity risk. Refiners can benefit from product scarcity even when crude prices soften, but feedstock availability and outages complicate the relationship. The most direct thesis remains about Brent and the shape of the oil curve.
Conclusion
The central mistake would be to treat the move above US$100 as either pure panic or a permanent new equilibrium. It is neither. The price is supported by a measurable loss of Gulf output, shrinking inventories and exceptional product tightness. Iran's leverage comes from making passage unsafe, expensive and administratively uncertain. That affects the marginal barrel even when some tankers continue to move in darkness.
The same market is also adapting. Pipelines, escorted routes, ship-to-ship transfers, emergency stocks and weaker demand have prevented a complete collapse in supply. Those mechanisms are expensive and incomplete, but they explain why the largest oil disruption in modern market history has not produced a permanently vertical price path. They also explain the sharp backwardation: scarcity is immediate, while relief is expected later.
Our position is therefore direct. Brent retains upside event risk over the next month, and the physical evidence supports a tactical constructive stance. Beyond that horizon, the burden of proof shifts. US$100-plus Brent becomes sustainable only if the war creates durable production loss or a permanently impaired export regime. Until deferred prices and actual 2027 output confirm that change, the better medium-term assumption is mean reversion through a volatile path. Oil prices respond to safe barrels that can reach refiners, not to declared capacity or political confidence.
US$95-115 by end of October
Series EIA: Europe Brent Spot Price FOB Entry 109.51 Target at or below 115.00 By 31 Oct 2026 Written 13 Sep 2026
Resolves against EIA series PET.RBRTE.D on the last observation on or before 31 Oct 2026. Not investment advice.
The Position
PARAMETER | 6:05 MARKETS VIEW |
|---|---|
Direction | Tactically constructive on Brent over the next month; lower and more neutral through 2027 |
Base range | US$95-115 in one month; US$85-100 at end-2026; US$70-90 2027 annual average |
Preferred benchmark | Brent, because it is more directly exposed to Middle Eastern seaborne supply than WTI |
Thesis works if | Hormuz exports stay constrained, Gulf shut-ins remain near 5-6 mb/d and product cracks stay elevated |
Downside invalidation | Insured flows recover for two weeks, physical premiums compress and Brent falls below roughly US$90 as the curve flattens |
Upside invalidation | Gulf output remains at least 4 mb/d below normal into 2027 and deferred Brent moves above US$100 |
Analytical confidence | Medium because physical tightness is confirmed but flow measurement and event timing remain unusually uncertain |